Skyrocketing Freight Costs Hamper Lumber Sales
Originally Published by: HBS Dealer —October 8, 2026
SBCA appreciates your input; please email us if you have any comments or corrections to this article.
As the usual slowdown for construction framing dimension softwood lumber sales occurred into late September, the situation of severely-strained inventories continued. It seemed like most folks were just waiting for the year to actually wind down into winter, and did not want to change their practice of not loading up their yards with wood.
The now multi-year habit of just-in-time buying seems to have become entrenched. While demand was low enough to justify this, the burgeoning situation of sharply-rising fuel costs started causing real problems. Customers who were satisfied with the sales prices abruptly balked when the cost of fuel surcharges were added to their orders.
Expect this to become a regular occurrence, as diesel prices will indeed rise further into the beginning of 2027.
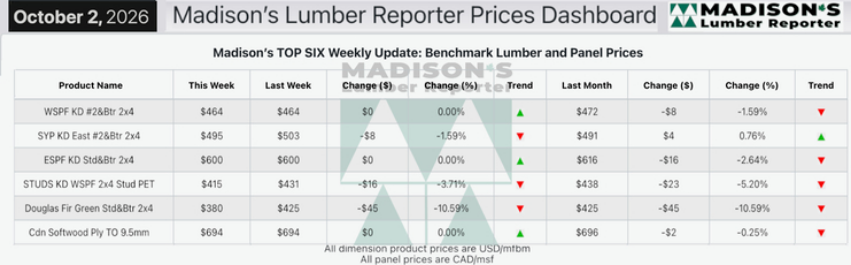
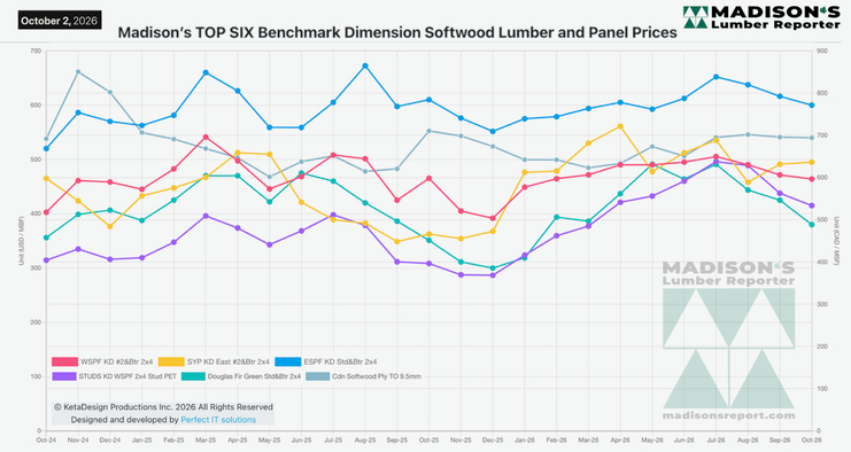
In the week ending October 02, 2026 the price of Western Spruce-Pine-Fir 2x4 #2&Btr KD (RL) was $464 mfbm, which was flat from the previous week, according to weekly forest products industry price guide newsletter Madison’s Lumber Reporter.
That week’s price was down -$8, or -2%, from one month ago when it was $472. Compared to the same week last year, when it was $436 mfbm, that price was up +$28 or +6%. Compared to two years ago when it was $404, that week’s price was up +$60, or 15%.
The next unknown is the arrival of storm season in the U.S., and what that will mean for property destruction (and thus rebuilding). There have been times in the past when re-roofing activity during December was high enough to prop up lumber sales somewhat.
In the week ending October 02, 2026, the price of Southern Yellow Pine East Side 2x4 #2&Btr KD (RL) was $495 mfbm. This was down -$8, or -2%, from the previous week when it was $503. That week’s price was up +$4, or +1%, from one month ago when it was $491.
Lumber pricing and market conditions takeaways for September 2026
- Western lumber markets showed paradoxical signs of stable instability.
- Buyers of Western-SPF in the U.S. continued to focus on their most short-term needs only.
- Sawmills attempted to draw a line in the sand on their asking prices.
- Large Canadian Western-SPF mills leaned on order files into late October and refused to budge on pricing.
- Logistics played a significant role with each order; freight costs and timelines could make or break deals.
- Demand for Eastern-SPF came in fits and starts while prices were relatively stable.
- Price vulnerability was apparent across the entire Southern Yellow Pine complex.
- Southern U.S. sawmills held tenuous lead times into early- or mid-October at best.
The Madison’s Lumber Prices Index for the week ending October 02, 2026 was: $505 mfbm. This was flat the previous week, and was down -4%, or -$20, from one month ago when it was $525.
The forest products and construction material industries continue to show concern about freight costs, as diesel prices hit levels not seen in recent times. Sellers cautioned reluctant customers that waiting until the last minute to place orders might not be the best plan, as the reduced purchase price could easily become eclipsed by sharply rising fuel rates.
Add to this the uncertainty of even sourcing trucks or rail cars, and altogether these conditions made the situation of delayed delivery a very real possibility.