August's Wholesale Prices Ticked Upward
Originally Published by: HBS Dealer — September 10, 2026
SBCA appreciates your input; please email us if you have any comments or corrections to this article.
 Softwood lumber pricing remained volatile in August, dipping 2.9 percent (month-over-month) after rising over 8 percent in July.
The Producer Price Index for final demand rose 0.4 percent in August (seasonally adjusted), according to data tracked by the U.S. Bureau of Labor Statistics.
Final demand prices rose 0.1 percent in July and decreased 0.1 percent in June. On an unadjusted basis, the index for final demand increased 5.4 percent for the 12 months ended in August.
In August, the index for final demand goods advanced 1.1 percent, and prices for final demand services increased 0.1 percent. The index for final demand leaving out foods, energy, and trade services rose 0.3 percent in August after moving up 0.4 percent in July.
For the 12 months ended in August, prices for final demand less foods, energy, and trade services advanced 4.7 percent.
As for building materials, softwood lumber pricing continued its volatile run, dipping 2.9 percent month-over-month. That drop comes after rising 8.2 percent the previous month.
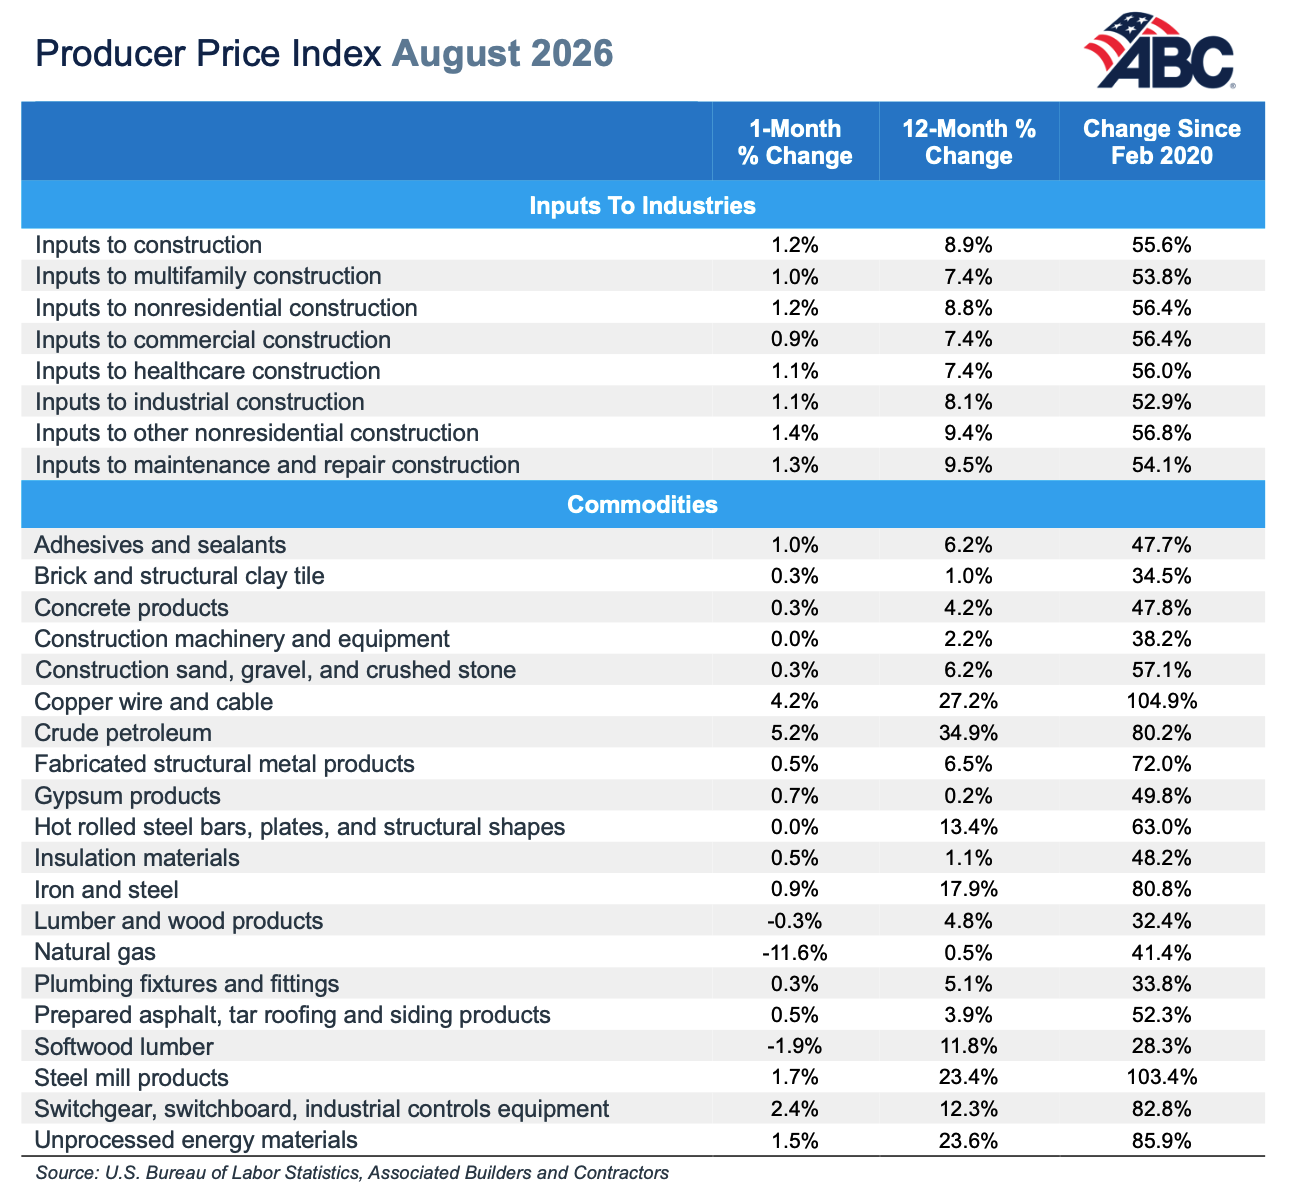
See below for recent pricing movement data on other key building materials (and the full dataset here).
Plumbing fixtures
Year-over-year (August 2025 to August 2026): +5.1%
%Month-over-month (July 2026 to Aug. 2026): +0.3
Hardware
Year-over-year: +4.0%
>Month-over-month: -0.1%
Hardwood Lumber
Year-over-year: +1.7%
Month-over-month: -0.9%
Lighting Fixtures
Year-over-year: +1.4%
Month-over-month: +0.1%
Softwood Lumber
Year-over-year: +11.8%
Month-over-month: -2.9%
Bolts, Nuts, Screws
Year-over-year: -4.0%
Month-over-month: 0.0%
Adhesives & Sealants
Year-over-year: +6.2%
Month-over-month: +1.0%
Plywood
Year-over-year: +10.7%
Month-over-month: +1.5%
Concrete Products
Year-over-year: +4.2%
Month-over-month: +0.3%
Millwork
Year-over-year: +3.9%
Month-over-month: -0.1%
On LinkedIn, Havas Edge Chief Economist Thomas J. Thompson shared more context on the latest PPI data release:
"Today’s report still shows elevated producer inflation, but it doesn’t give us strong evidence of a new broad-based acceleration and now tomorrow gets interesting because CPI will give us the other side of the inflation picture. If consumer prices also show inflation broadening, today’s 5.4% PPI reading becomes harder to dismiss. If they don’t, August may look more like an energy-driven producer price spike than the beginning of another broad inflation acceleration.
On the construction side of things, ABC Chief Economist Anirban Basu wrote: “Construction input prices surged again in August, and the increases were widespread across materials. Prices for iron and steel, softwood lumber, switchgear, copper wire and cable, and several derivative metal products are now up more than 10% year over year. While contractors remain optimistic about their margins ... ongoing input price escalation is likely to weigh on profitability over the next several months. This is especially true given recent escalation in the trade war with Canada and the fact that oil prices have jumped back above $100 per barrel.”
ABC shared the following pricing breakdown of vital materials.