Softwood Lumber Market Shows 'Quiet Strength'
Originally Published by: HBS Dealer — September 10, 2026
SBCA appreciates your input; please email us if you have any comments or corrections to this article.
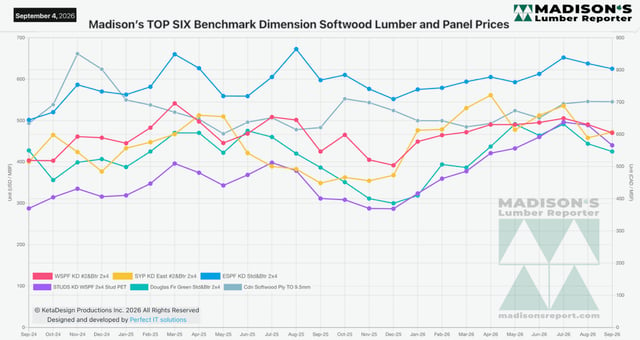
Even as, in advance of Labor Day, the North America construction framing dimension softwood lumber market was in the usual snoozy mode, the price of benchmark lumber commodity item Western S-P-F 2x4 crested higher than the same week last year. And landed quite a bit above the same time in 2024.
This nice even trend line over the course of two entire years provides a good stability for sawmills in Canada and the U.S. to see where the market is and make their plans for the next upcoming new homebuilding season in spring of 2027.
In that time, the high for this item was $550 mfbm in mid-March 2025, and the low was $388 in October 2024. A spread of $162 is a bit higher than historical over the course of a year, but it's still much less volatile than the recent several years.
In essence: This development provides a baseline for the industry to know the range of price high vs. price low that will be likely going forward.
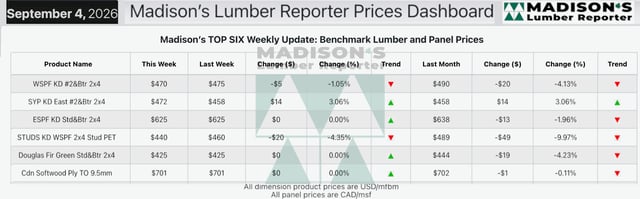
In the week ending September 04, 2026 the price of Western Spruce-Pine-Fir 2x4 #2&Btr KD (RL) was $470 mfbm, which was down -$5, or -1% from the previous week when it was $475, according weekly forest products industry price guide newsletter Madison’s Lumber Reporter. That week’s price was down -$20, or -4%, from one month ago when it was $490. Compared to the same week last year, when it was $420 mfbm, that price was up +$50, or +2%. Compared to two years ago when it was $403, that week’s price was up +$72, or +20%.
While prices did not make much movement, the state of the North American construction framing dimension softwood lumber market leading up to Labour Day demonstrated a quiet strength.
In the week ending September 04, 2026, the price of Southern Yellow Pine East Side 2x4 #2&Btr KD (RL) was $472 mfbm. This was up +$14, or +5%, from the previous week when it was $458. That week’s price was up +$14, or +3%, from one month ago when it was $458.
Key lumber market takeaways for September 2026:
- Lean field inventories continued to support an uneasy truce between supply and demand.
- Players were adamant the market could turn on a dime if half-decent autumn demand materializes.
- Significant variations appeared between US Western-SPF suppliers, regions, and origin-destination pairings.
- In Canada, prices on key Western-SPF 2x4 dimension items wavered around the previous week’s levels.
- According to Eastern-SPF suppliers, the Toronto region was a "basket case" while the Great Lakes market was flat.
- Plenty of distributors in the Northeast deeply discounted items to keep unwanted stock moving.
- Prices of Southern Yellow Pine narrows continued to lead the way back up after precipitously dropping during summer.
- On the U.S. Eastern seaboard, inventory holders showed varying levels of urgency to move material.
The Madison’s Lumber Prices Index for the week ending September 04, 2026 was: $518 mfbm. This was down -1%, or -$3, the previous week when it was $518, and was down -3%, or -$18, from one month ago when it was $536. Interestingly, this was up +9%, or +$41, from the end of August one year ago when it was US$477.
As looming demand was improving, the expectation was that prices would increase somewhat in coming weeks. The situation with severely depleted inventories continued, meaning customers still had to search around widely to source the particular mix of wood they needed.
Meanwhile, the usual seasonal constraints to transportation materialized, particularly with trucking. As autumn comes on every year, other goods and products take precedence in the supply chain over lumber. This combination of lower supply and lack of trucks made for increased urgency as buyers had to wait for the wood they needed yesterday.